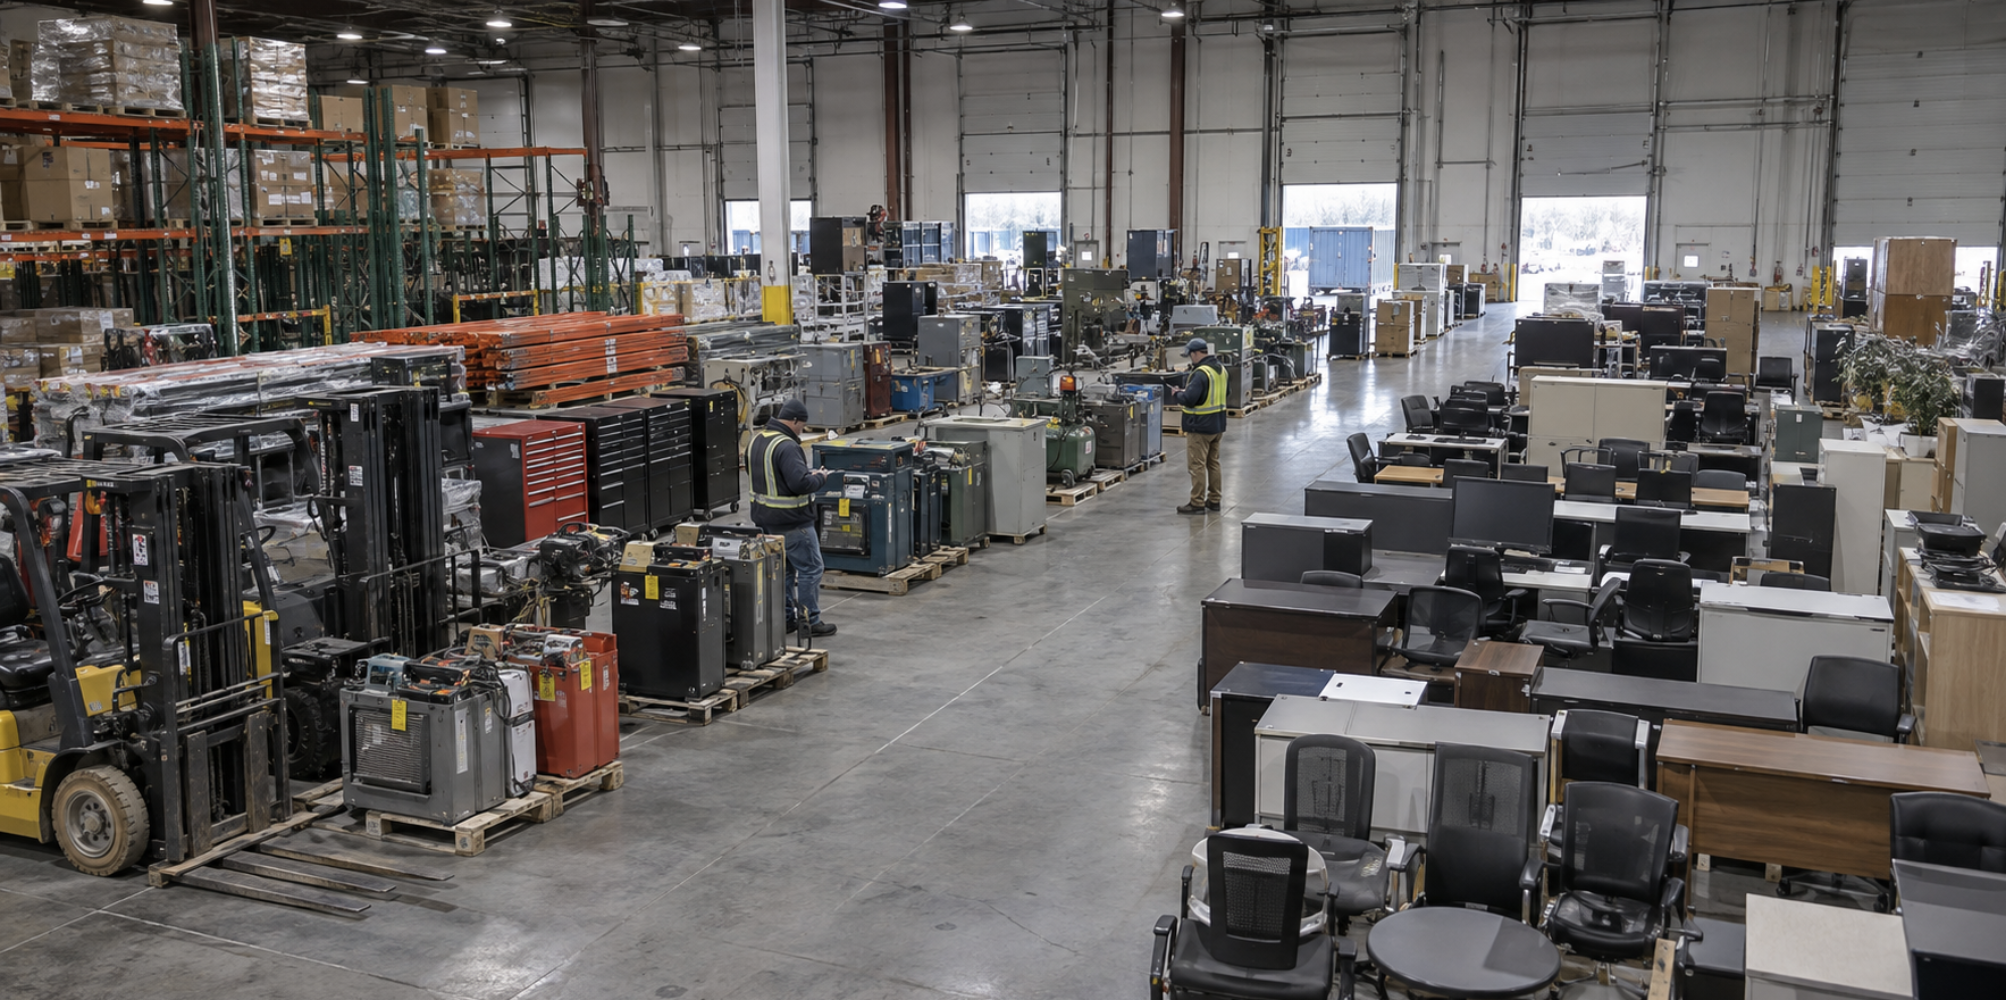
The benefits of selling surplus business assets include releasing cash, reducing avoidable expenses and making room for equipment or activities the business still needs. For Canadian companies, selling unused furniture, machinery or inventory can support a relocation, downsizing project or operational change without requiring the business to close.
The financial benefit depends on what the assets can sell for, the costs of preparing and removing them, and whether the business will need them again. A useful sale produces a worthwhile overall result, not simply an attractive selling price.
Before committing assets to a buyer, compare the expected recovery with the cost of keeping, redeploying or replacing them.
Selling Surplus Assets Does Not Require Closing the Business
Liquidation is often associated with bankruptcy or company closure. However, commercial asset liquidation can also involve selling items that an operating business no longer requires.
Examples include furniture left after an office consolidation, machinery replaced by newer equipment, or inventory from a discontinued product line. The company may continue operating while those assets move to another owner.
Selling surplus items should not be confused with formally winding up a corporation or entering an insolvency proceeding. If either process is involved, confirm who has authority to approve the sale before proceeding.
MGT’s Commercial Asset Liquidation service addresses the physical assets involved in business transitions. The starting point is identifying what is genuinely surplus and what still serves an operational purpose.

How Selling Unused Equipment Improves Cash Flow
Unused equipment may have resale value, but that value cannot pay a supplier until a sale is completed and payment is received.
Selling converts the asset into a cash receipt. BDC identifies selling unused equipment and machinery as one tactic businesses can consider in its cash-flow planning guide.
To understand how much a sale could contribute, separate three figures:
- Gross proceeds: The selling price of the assets before deductions.
- Project costs: Applicable seller-paid expenses, such as selling fees, preparation, dismantling, transport and clearance.
- Net recovery: Gross proceeds less those relevant project costs.
For example, a sale generating $20,000 with $4,000 in seller-paid costs would produce $16,000 in project-level net recovery. This is an illustration, not a market estimate. It does not account for taxes or financing obligations that may need to be settled.
Timing matters as much as the amount. Confirm when payment is due and whether expenses must be paid before sale proceeds arrive.
An asset sale provides a one-time cash inflow. It may ease a short-term cash shortage, but it does not by itself resolve recurring operating losses or demonstrate that the business has become more profitable.
Reduce Avoidable Costs and Reclaim Useful Space
Costs That Can Actually Stop
Keeping unused assets may involve storage, maintenance, insurance or handling expenses. Selling them can reduce those costs where the expense genuinely ends or decreases after removal.
The saving needs to be checked rather than assumed. Removing one machine may not change a bundled insurance premium. Clearing a storage area may not reduce rent under an existing lease.
List the expenses associated with the assets and identify which can actually be cancelled or reduced. Compare those potential savings with the cost of selling and clearing the items.
This distinction prevents a planning estimate from counting expenses that the business will continue paying anyway.
Space With a Practical Use
Selling surplus assets can release floor space for current operations, new equipment or a more efficient layout.
That operational benefit can matter even where rent remains unchanged. However, it should be described separately from a cash saving.
Identify the intended use before assigning a financial value to the space. Will removing redundant shelving make room for active stock? Can an unused machine be removed to accommodate equipment already scheduled for installation?
If there is no planned use and no reduction in occupancy costs, the benefit may be a clearer workspace rather than an immediate financial return.
Put Recovered Funds Toward Current Priorities
Cash recovered from surplus assets may help fund operating needs, replacement equipment or a business transition.
The appropriate use depends on the company’s obligations and cash forecast. Proceeds may already be needed for sale expenses, financing arrangements or other liabilities, so the full selling price should not automatically be treated as freely available cash.
Before allocating proceeds to owners or another venture, ask the company’s accountant to confirm the appropriate treatment.
A practical approach is to identify the intended use of the expected net proceeds before accepting an offer. This makes it easier to judge whether the proposed payment date and removal arrangements meet the business’s needs.

Check Whether Selling Is Better Than Keeping or Redeploying
Unused does not always mean unnecessary. A machine may provide backup capacity, support seasonal work or be suitable for another location.
Before selling, consider:
- Future demand: Is there a credible plan to use the asset again?
- Internal alternatives: Could another department or site use it instead of buying equipment?
- Replacement cost: What would it cost to replace or rent the asset if it were needed later?
- Current recovery: What is the likely selling price, less seller-paid sale and removal costs?
- Holding costs: Which expenses continue while the asset remains unused?
Keeping equipment “just in case” can postpone a useful sale. Selling something that must be replaced shortly afterwards can also be expensive.
The decision should reflect realistic operational needs rather than the original purchase price alone. Where ownership, financing or sale authority is unclear, resolve those questions before offering the asset to buyers.
Tax and Personal-Liability Limits to Understand
A Sale Does Not Guarantee a Tax Deduction
Selling an asset for less than its original purchase price does not automatically create a deductible capital loss.
The CRA’s T2 Corporation Income Tax Guide distinguishes between capital losses, terminal losses and recapture of capital cost allowance.
For depreciable property, a disposal loss is not treated as a capital loss. A terminal loss may arise when no property remains in the relevant class at year-end and a positive undepreciated capital cost balance remains, subject to applicable exceptions. A sale can instead result in recapture that must be included in income, and a capital gain may also arise.
Net capital losses generally apply against taxable capital gains. Do not assume that a corporate loss can offset income from an owner’s personal venture or an unrelated business.
Have an accountant assess the actual assets and tax records before including a tax saving in the financial case for a sale.
Liquidation Does Not Automatically Remove Personal Liability
Selling company assets does not itself eliminate a director’s potential liability for unpaid remittances.
The CRA’s Director’s Liability guidance explains circumstances in which directors may be personally liable for specified amounts the corporation failed to deduct, withhold, remit or pay.
The applicable rules contain conditions, limitations and defences. This does not mean directors automatically owe every company debt, but liquidation should not be promoted as a guaranteed way to protect personal finances or credit.
Where the business is financially distressed, establish the appropriate legal and financial process before arranging asset sales.
Plan the Sale Around Net Recovery
Begin with an inventory showing the assets, quantities, condition, location and available records. Photographs, model numbers and known defects help buyers assess what is being offered.
Next, estimate a realistic selling value. How to Calculate Liquidation Value provides related valuation background. For your sale budget, keep the estimated asset proceeds separate from selling expenses and company liabilities.
Choose a sale method that fits the inventory and deadline. An auction may suit assets with several likely buyers, while a negotiated sale may be more practical where a buyer wants an entire group. MGT’s Liquidation Auctions in Canada guide explains the process and trade-offs.
Compare proposals using the same scope. Confirm what each buyer will take, when payment will arrive, who pays for removal and what happens to anything left behind. Count each project expense once.
Coordinate collection with employees whose work could be affected. Retain sale agreements, invoices and removal records so the business can reconcile what was sold and what it received.
Discuss Your Surplus Assets With MGT
Selling surplus business assets can release cash and simplify operations when the expected recovery justifies the costs and the equipment is no longer needed.
Contact Michaels Global Trading with your asset list, photographs, location and preferred removal date to discuss suitable sale and clearance options.