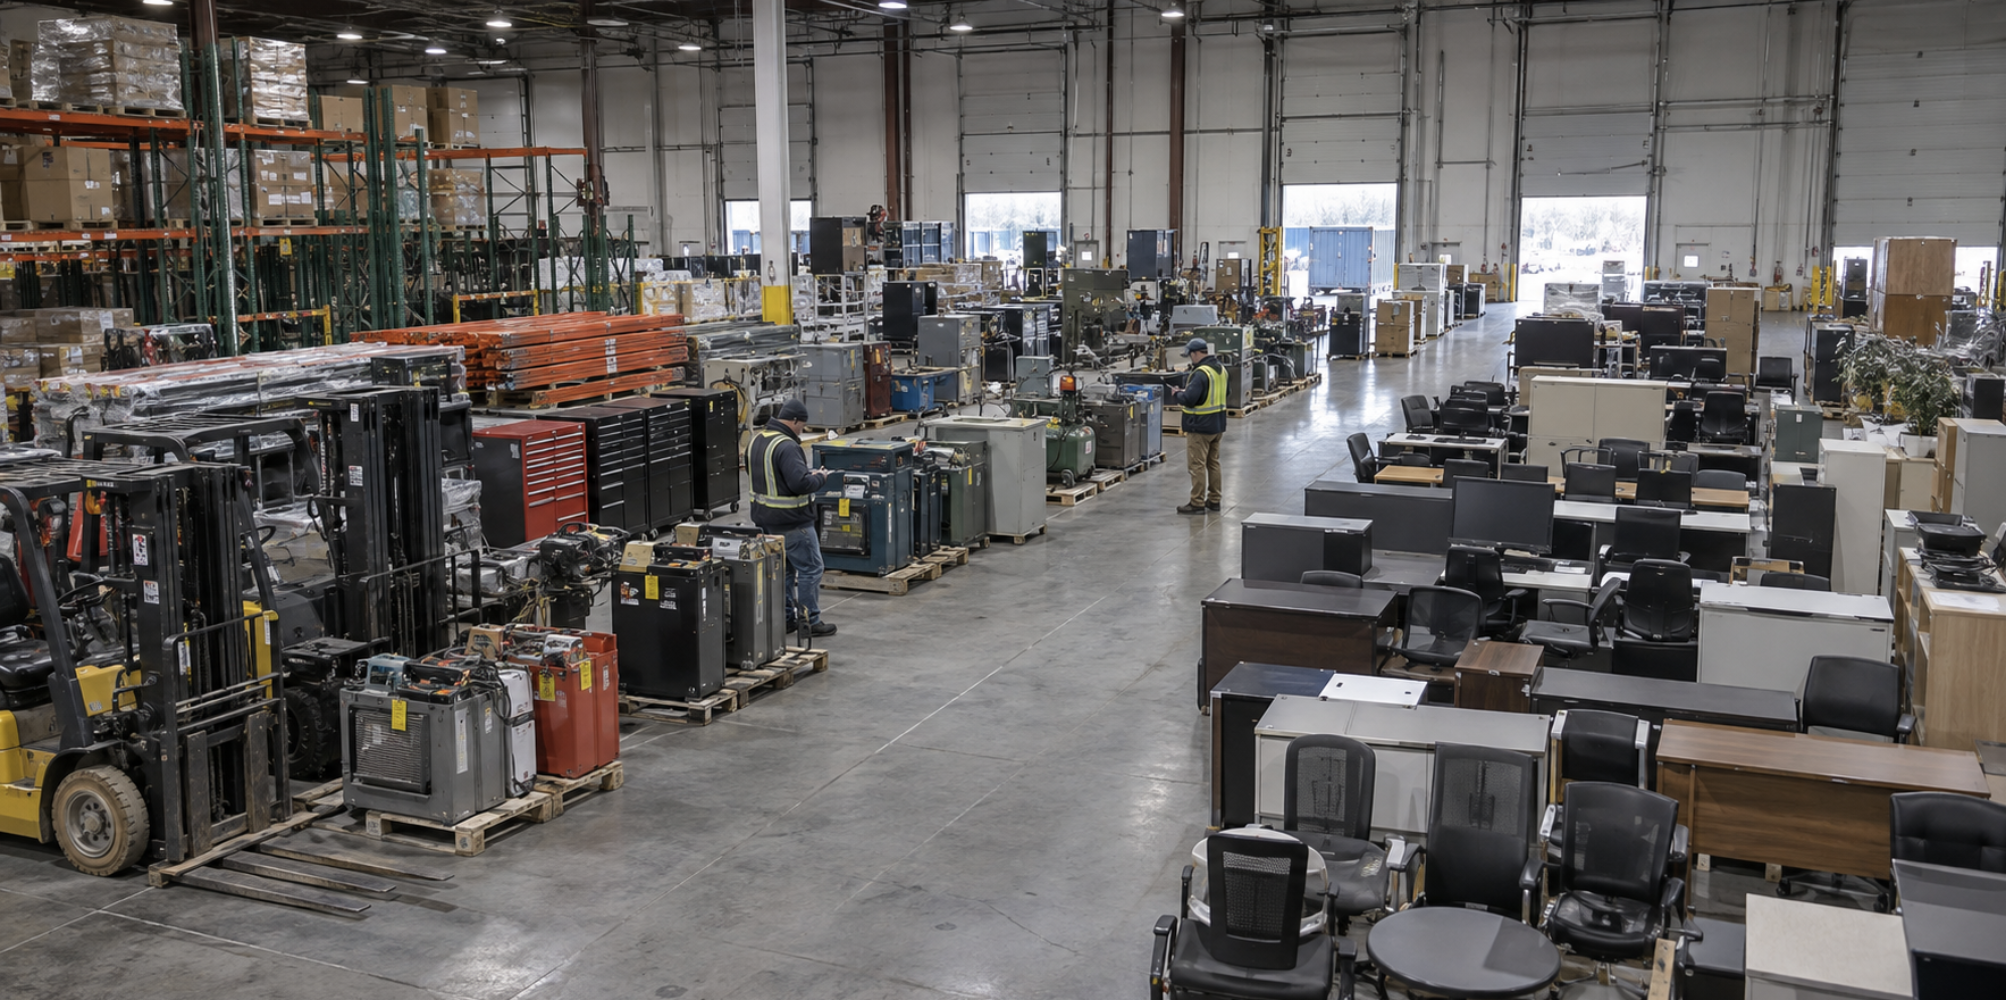
To calculate the liquidation value of your assets, estimate what each item or group could sell for under defined sale conditions and a realistic timeline. Add those estimates to establish expected gross proceeds. Then subtract the selling and removal costs you would pay to estimate project net recovery.
A useful liquidation value calculator needs realistic inputs. Original purchase prices and blanket discounts cannot tell you what buyers will pay today. Whether you are clearing office furniture, inventory or equipment, the calculation should reflect condition, demand, location and the time available to sell.
What Does Liquidation Value Measure?
Liquidation value estimates what assets could realise under particular sale conditions. It is different from book value, which is an accounting figure, and from the value of an operating business with future earnings.
The International Valuation Standards Council glossary describes liquidation value in terms of assets sold individually or in parts. For planning purposes, identify exactly which assets your estimate covers and whether the reported amount includes selling expenses.
Asset value, net recovery and company equity answer different questions. Estimating gross proceeds from surplus equipment does not involve subtracting every debt the business owes. Determining what might remain for owners after a company winds down is a separate exercise involving its wider assets, liabilities and obligations.
Orderly Versus Forced Liquidation
An orderly liquidation allows reasonable time to find buyers. A forced-sale scenario involves a seller compelled to sell with a shortened marketing period. The distinction concerns the circumstances of the sale, not simply whether an auction is used.
BDC’s equipment valuation guide describes orderly and forced liquidation equipment values as estimated gross amounts. That makes it important to show costs separately when working towards a net figure.
An auction can be one sales option. MGT’s Liquidation Auctions in Canada guide explains the process and its trade-offs.

How to Calculate Liquidation Value Step by Step
1. Define the Assets and Sale Conditions
Start with the purpose of the estimate, its date and the deadline for selling and collecting the assets. Specify whether you are selling selected surplus items or clearing an entire location.
Prepare an asset list that records:
- Description, manufacturer, model and quantity.
- Age, condition, known faults and missing components.
- Photographs and available maintenance or testing records.
- Location, access restrictions and collection deadline.
Identify anything excluded from the proposed sale. For fixtures and equipment, clarify whether the estimate assumes they remain installed or require dismantling and removal.
2. Research Comparable Sales
Look for evidence of what similar assets have sold for. Dealer listings can provide context, but an asking price is not proof of a completed transaction.
BDC explains that appraisers may compare market sales and adjust for age, condition, remaining useful life and other differences. For your preliminary estimate, record where each comparison came from and why it is relevant.
Compare like with like. A working machine with service records may not be comparable to an untested unit. Similarly, the price for one item may not apply when selling a large mixed lot. Note whether comparable prices include fees, delivery or other services that your proposed sale excludes.
3. Build a Supported Range
Where the evidence is uncertain, prepare a lower and upper estimate rather than presenting one precise figure. Explain the assumptions behind each.
For example, one scenario might allow individual sales over a longer period, while another assumes a bulk sale before a fixed clearance date. Do not automatically apply the same discount to every asset.
Keep asking prices, estimated sale proceeds and actual buyer offers clearly labelled. An offer also needs its conditions checked, including inspection, collection and payment terms.
4. Estimate Selling and Removal Costs
Ask which expenses you would pay under each arrangement. Depending on scope, these could include sale fees, preparation, dismantling, labour, transport, storage and handling unsold material.
MGT’s Commercial Liquidation Costs in Canada guide separates estimated recovery from project costs. Use the same distinction when comparing proposals.
Avoid deducting an expense twice. If an offer already includes collection or represents a net payment after fees, establish what remains outside that figure before making further deductions.

A Simple Liquidation Value Calculator Example
You can organise a preliminary calculation in a spreadsheet or written worksheet. Use separate entries for each asset category and each applicable cost.
The following figures are illustrative Canadian-dollar amounts, not market benchmarks or an MGT quote:
- Estimated furniture proceeds: $8,000.
- Estimated equipment proceeds: $15,000.
- Estimated inventory proceeds: $7,000.
- Total estimated gross proceeds: $30,000.
- Selling and preparation costs: $2,000.
- Removal and transport costs: $3,000.
- Residual clearance costs: $1,000.
The calculation is:
Estimated net recovery = $30,000 − $6,000 = $24,000.
This example excludes tax and debt settlement. Its purpose is to show how estimated sale proceeds and project expenses fit together.
The $24,000 is not necessarily profit, because it does not account for what the business originally spent acquiring the assets. If actual costs exceed proceeds, the project would require a payment rather than produce positive net recovery.
Repeat the calculation for each realistic sale scenario, using the costs associated with that scenario. More time to sell may change both the proceeds and the expenses, so compare the final net figures.
What Changes the Estimate for Inventory and Equipment?
Inventory needs more than a category label. Record quantities, packaging condition, product age, completeness and any relevant expiry dates. Separate unused stock from returns and damaged goods so that buyers can assess what is being offered.
Equipment estimates should reflect operating condition, specifications, maintenance history and removal requirements. BDC notes that specialised equipment without an active resale market may require a different valuation method from equipment with readily available sales comparisons.
Do not treat book value as a guaranteed starting price. A fixed percentage applied to every category can conceal important differences between assets.
Consider the whole clearance scope, too. A buyer’s offer for desirable items may leave other stock or equipment behind. Include the cost of dealing with those remaining items when comparing options.
When Is a Commercial Asset Appraisal Useful?
A preliminary calculation can help with internal planning. A commercial asset appraisal may be useful when assets are specialised, comparable evidence is limited or another party needs a documented valuation.
Before commissioning a liquidation appraisal, explain its intended use. Ask the appraiser to identify the valuation date, assets covered, assumed sale period, market evidence and treatment of costs.
If a lender or insurer will rely on a valuation, confirm the required basis of value and report requirements first. Liquidation value may not be the appropriate measure for that purpose. A sale offer, project quote and formal appraisal are not interchangeable.
For a commercial clearance enquiry, prepare your asset list, photos and timing requirements. MGT’s Commercial Liquidation Process guide explains how assessment connects with sale planning and removal.
Turn Your Estimate Into a Liquidation Plan
A useful estimate shows both the potential proceeds and the work needed to achieve them. MGT’s Commercial Asset Liquidation service covers surplus business assets across office, retail and warehouse settings.
Contact Michaels Global Trading with your asset list, photographs, location and clearance deadline to discuss the project scope and available options.