
Tax Benefits of Donating Office Furniture in Canada: A Guide for CFOs
Learn the CRA rules and tax benefits of donating office furniture in Canada, including fair market value, appraisals, charitable deductions, and tax receipts.
Donating surplus office furniture can create a tax benefit for a Canadian corporation while providing a useful alternative to disposal. When qualifying furniture is transferred to a registered charity or another qualified donee, the recipient may issue an official donation receipt based on the eligible value of the gift.
For corporations, that receipt can support a charitable donation deduction, rather than the personal charitable tax credit available to individuals. The Canada Revenue Agency generally allows corporations to deduct eligible charitable donations up to 75% of net income, with unused amounts normally available to carry forward for five tax years. CRA's T2 Corporation Income Tax Guide (Canada)
The tax benefit is only one part of the decision. CFOs also need to consider fair market value, the company's tax basis in the furniture, potential capital cost allowance consequences, transportation costs, and whether the receiving organization can actually accept the inventory.
How the Corporate Tax Benefit Works
A corporation donating qualifying property to a registered charity or another qualified donee may claim the eligible amount of the donation as a deduction when calculating taxable income.
CRA guidance confirms that qualified donees can issue official donation receipts to corporations and that corporations may claim a charitable deduction based on eligible gifts. CRA guidance for donors (Canada)
The key word is deduction.
If a corporation receives a $20,000 donation receipt, that does not mean it receives $20,000 back in tax savings. The eligible amount reduces taxable income, subject to the applicable donation limits and the company's overall tax position.
That distinction should remain clear in any internal business case comparing donation with resale or disposal.
The 75% Net Income Limit
CRA's current T2 guidance states that the maximum charitable donation deduction for a corporation is generally 75% of net income for the taxation year. The limit can be increased in certain situations involving donations of capital property or depreciable property. Unused charitable donations can generally be carried forward for up to five following tax years. (Canada)
For a CFO, this creates three practical questions:
- Does the corporation have enough taxable income to use the deduction this year?
- Would part of the donation need to be carried forward?
- Are there additional tax consequences from disposing of depreciable furniture?
If the corporation has nil net income or a loss, CRA notes that a charitable donation deduction cannot be used to create or increase that loss, although the unused donation may generally be carried forward. (Canada)
Fair Market Value Determines the Donation Receipt
Office furniture is a non-cash gift, commonly referred to as a gift in kind.
The donation receipt is not based on what the company originally paid for the desks, chairs, or workstations. It is generally based on their fair market value at the time of donation, subject to CRA's deemed fair market value rules where applicable.
CRA defines fair market value as the highest price property would normally bring in an open and unrestricted market between knowledgeable, informed, independent parties acting prudently. CRA guidance on determining fair market value (Canada)
For office furniture, value can be affected by:
- manufacturer and model
- age
- condition
- quantity
- matching sets
- completeness
- style and finish
- current secondary-market demand
A five-year-old task chair may still have meaningful market value. A large custom workstation system designed around one specific floorplan may be much harder to place.
When Should Office Furniture Be Professionally Appraised?
CRA strongly recommends an independent professional appraisal when the expected fair market value of donated property is more than $1,000.
For property below that level, someone with sufficient knowledge of the property may be able to establish fair market value. When an appraisal is used, the appraiser's name and address must appear on the official receipt. (Canada)
For a commercial office donation, the combined inventory can easily exceed $1,000 even when individual pieces are relatively modest.
A CFO should therefore establish the valuation method before the furniture leaves the premises.
Keep:
- the final furniture inventory
- photographs
- appraisal documentation where applicable
- the official donation receipt
- confirmation of the receiving organization
- transportation and removal records
That provides a much stronger audit trail than attempting to recreate the inventory after the office has been emptied.
Confirm the Recipient Can Issue a Tax Receipt
Not every nonprofit organization can issue an official donation receipt.
CRA states that registered charities and other qualified donees can issue donation receipts that corporations may use for charitable deductions. The CRA maintains searchable lists so businesses can verify an organization's status. CRA's qualified donee listings (Canada)
This should be checked before the furniture is transferred.
Also confirm that the organization actually intends to issue a receipt. CRA notes that qualified donees are permitted to issue official receipts, but they are not necessarily required to provide one for every donation. (Canada)
For multi-location projects, MGT's office furniture donation services coordinate inventory review, removal, transport, and delivery to suitable organizations. Charity receipts remain recipient-issued when available. (Michaels Global Trading)
Understand the Tax Treatment of the Furniture Itself
This is where the calculation becomes more important for CFOs.
Commercial office furniture is generally depreciable business property. Donating depreciable property is not simply a charitable deduction transaction. The disposition of the asset can also affect its capital cost allowance treatment.
CRA's corporate guidance specifically recognizes that donating depreciable property can result in recapture of capital cost allowance, and its donation-limit rules can be adjusted where recapture arises from a qualifying donation. (Canada)
CRA's broader guidance on gifts of capital property also notes that disposing of depreciable property can result in CCA recapture or, depending on the circumstances, a terminal loss. CRA's Gifts and Income Tax guide (Canada)
For that reason, do not evaluate the donation solely from the face value of the charitable receipt.
Have your accountant compare:
- the furniture's fair market value,
- its remaining tax basis and CCA position,
- the charitable deduction available,
- any resulting recapture or other tax consequences, and
- the alternative recovery available through resale.
Donation Receipt Value vs. Resale Value
Donation and liquidation create different forms of recovery.
With resale, the business receives cash.
With donation, the business may receive an official charitable donation receipt that supports a deduction, while the furniture is transferred to a receiving organization.
Those are not financially equivalent.
Consider a simplified example. Suppose a furniture inventory has a supported fair market value of $15,000.
A donation could potentially produce a charitable receipt based on the eligible amount of the gift. A liquidation offer might instead produce a cash payment below that amount.
It would be incorrect to conclude that the $15,000 donation is automatically more valuable because the receipt is higher than the cash offer. The actual tax benefit depends on the corporation's tax situation, while resale produces cash directly.
For furniture with stronger secondary-market demand, run office furniture liquidation alongside the donation assessment rather than deciding on one route before understanding both outcomes. MGT's process evaluates resale potential first and can route suitable remaining furniture toward donation or recycling. (Michaels Global Trading)
Watch the Deemed Fair Market Value Rules
CRA has specific rules that can limit the receiptable value of certain non-cash gifts.
In some circumstances, the deemed fair market value may be the lesser of the property's actual fair market value and the donor's cost or adjusted cost base. The rules can apply, for example, when property was acquired less than three years before donation or was acquired within ten years with one of the main purposes being to donate it. CRA's deemed fair market value guidance (Canada)
For ordinary older office furniture acquired for business use, this may not be the central issue. But CFOs managing recent acquisitions or unusual transactions should check the rule rather than assuming current market value will always equal the receiptable amount.
Donation Logistics Still Have a Cost
A charitable receipt does not make removal free.
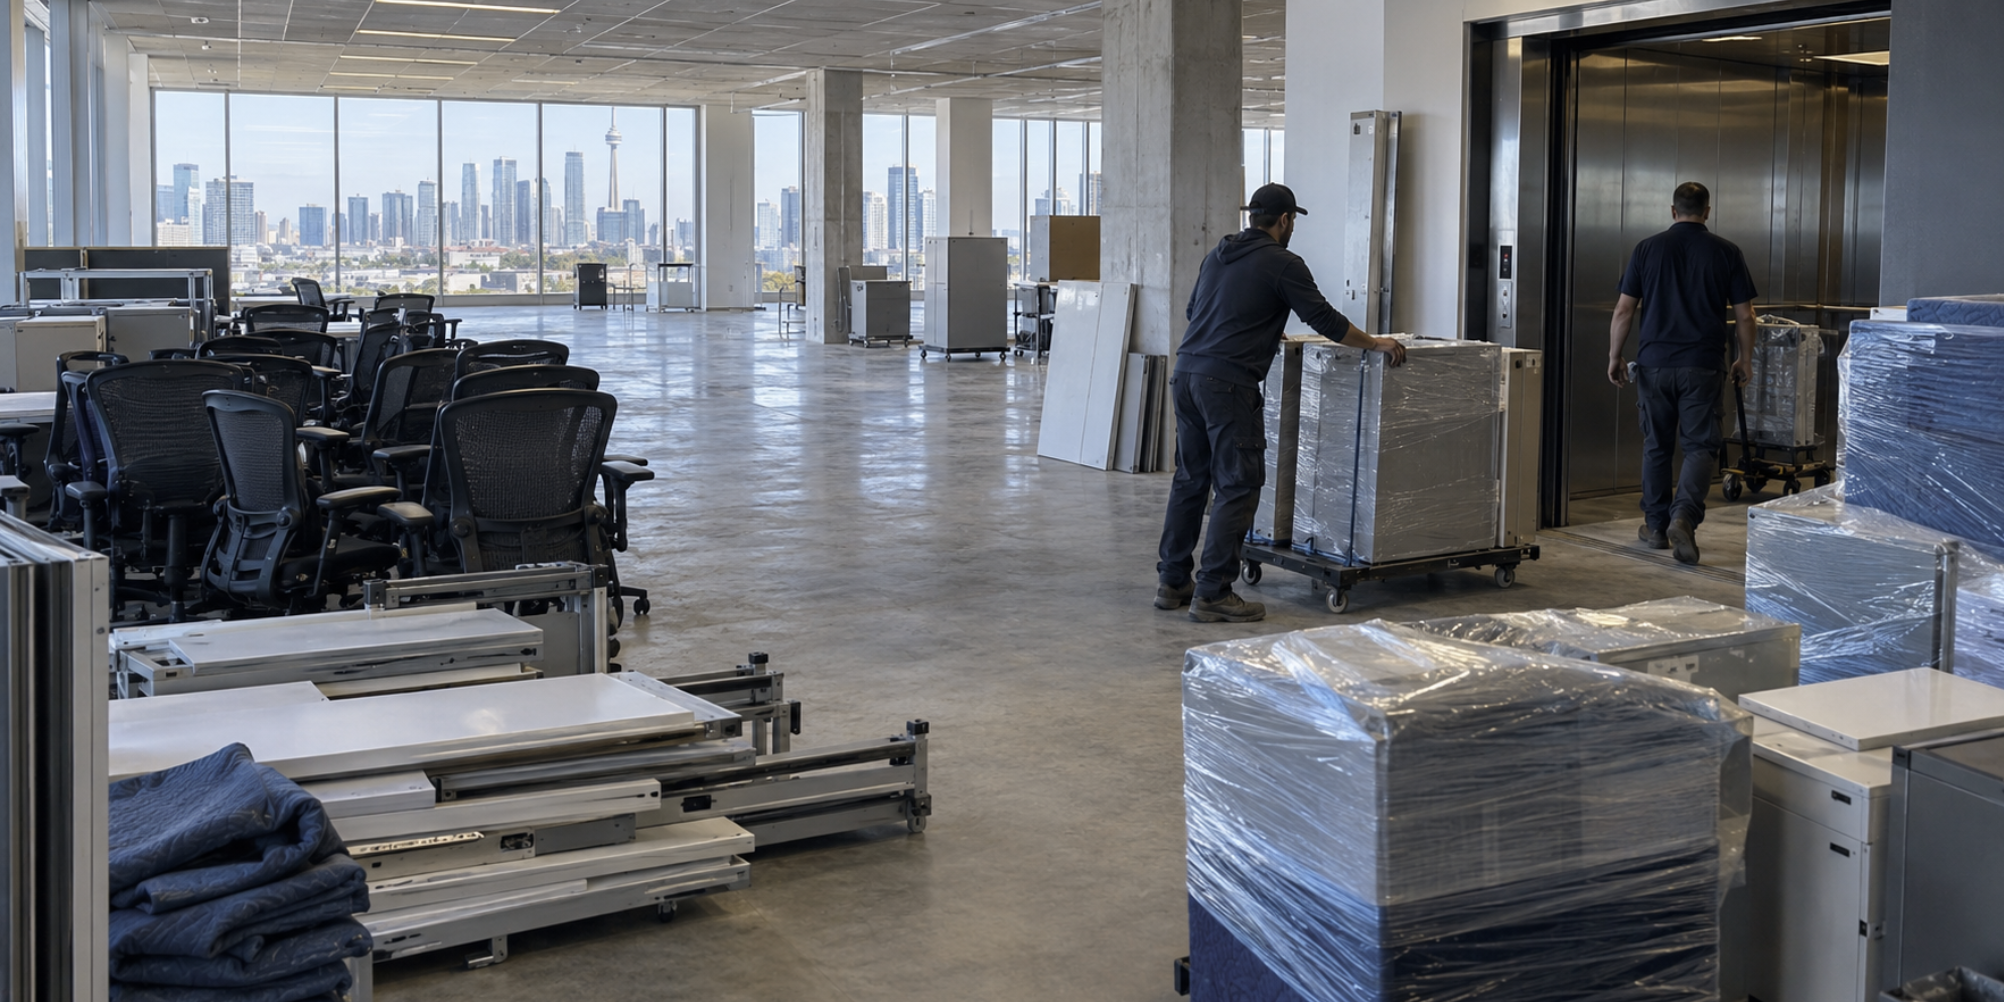
Commercial furniture may still need to be:
- inventoried
- dismantled
- moved through the building
- loaded
- transported
- delivered to multiple recipients
Receiving organizations also have capacity and condition requirements. Usable furniture can still be declined if the recipient has no current need or cannot absorb the quantity.
MGT's province-by-province guide to donating office furniture outlines how regional acceptance and pickup availability vary across Canada. (Michaels Global Trading)
Include those logistics in the financial comparison.
A useful CFO-level calculation is:
Net donation benefit = estimated tax benefit from the eligible charitable deduction minus the business's donation and removal costs
Compare that with:
Net resale recovery = sale proceeds minus selling and removal costs
The better route can differ across the same office inventory.
A Practical Donation Process for CFOs
Keep the process simple.
1. Inventory the Furniture
Record quantities, condition, photographs, manufacturers where known, and the location of the furniture.
2. Separate Resale Candidates
Identify furniture with meaningful market demand before committing the whole inventory to donation.
3. Confirm Recipient Eligibility
Verify that the intended organization is a registered charity or other qualified donee and confirm whether it will issue an official receipt.
4. Establish Fair Market Value
Use a supportable valuation process. For higher-value gifts, consider CRA's recommendation for an independent appraisal.
5. Review the Tax Position
Have the company's tax adviser review the expected charitable deduction together with the furniture's CCA position and any possible recapture.
6. Coordinate the Transfer
Confirm exactly what the organization will accept and schedule removal around the lease or office-transition deadline.
7. Reconcile the Records
Match the final donation receipt and delivery confirmation back to the original inventory.
Frequently Asked Questions About Donating Office Furniture in Canada
Can a Canadian corporation deduct donated office furniture?
Potentially, yes. Corporations can claim eligible donations to registered charities and other qualified donees as charitable deductions, subject to CRA rules and applicable limits. The general corporate limit is 75% of net income, with certain adjustments possible for gifts of capital property. (Canada)
Is the tax receipt based on the original cost of the furniture?
No. For a qualifying non-cash gift, the receipt generally reflects fair market value at the time of donation, subject to CRA's deemed fair market value rules. (Canada)
Do we need an appraisal?
CRA strongly recommends an independent professional appraisal when donated property is expected to have a fair market value above $1,000. (Canada)
Can any nonprofit issue a charitable tax receipt?
No. Confirm that the recipient is a registered charity or another qualified donee authorized to issue official donation receipts. (Canada)
Should we donate furniture instead of selling it?
Not automatically. Compare the expected cash recovery from liquidation with the tax benefit and costs associated with donation. Different pieces within the same inventory may be better suited to different routes.
Quick Recap
- Corporations receive a deduction, not an individual charitable tax credit.
- The general corporate deduction limit is 75% of net income, subject to certain adjustments.
- Unused qualifying donations can generally be carried forward for five years.
- Furniture is valued at fair market value, not its original purchase price.
- CRA recommends professional appraisal above $1,000.
- Only qualified donees can issue valid donation receipts.
- Depreciable furniture can have additional CCA tax consequences.
- Compare donation with resale on a net basis, not by comparing receipt value directly with a cash offer.
Get Your Office Furniture Donation Assessed
Michael's Global Trading can coordinate your office furniture donation, including inventory review, removal, transportation, recipient coordination, and certified appraisal support where required. MGT's current donation process also provides confirmation documentation on request.
Contact us with your inventory, photographs, location, and clearance deadline. We'll help assess the furniture, coordinate an appropriate donation recipient, and support the valuation process. Any official charitable tax receipt is issued by the receiving qualified donee, not by MGT.
Recommended Readings
A Province-by-Province Guide to Donating Office Furniture in Canada
Office Furniture Disposal Costs Exposed: Landfill Fees, Labour, and Lost Value
Recommended readings:
Blogs & News


Get started on
your journey with us.